Your home was broken into. Valuables are gone. And now your insurer is asking for—what feels like—a dissertation just to process a basic claim. The stress is real. But here’s the kicker: most claims get delayed or denied not because of fraud, but because of missing or poorly organized Burglary Claim Documentation Requirements. The good news? There’s a smarter way.
Why Your Burglary Claim Gets Stuck in Limbo
Insurance companies aren’t out to screw you—but their systems reward precision, not emotion. File with blurry photos, vague lists, or unsigned forms, and you’ll vanish into review purgatory. And that “prompt investigation” clause in your policy? It cuts both ways. They expect speed from you too—even while you’re reeling from trauma.
Think about it: if you can’t prove something existed, insurers legally don’t have to pay for it. Period. No drama. No sympathy. Just cold, hard paperwork.
Burglary Claim Documentation Requirements: A Step-by-Step Playbook
Forget the boilerplate checklists. This is what actually moves the needle.
Step 1: Secure the Scene (Before Cleaning)
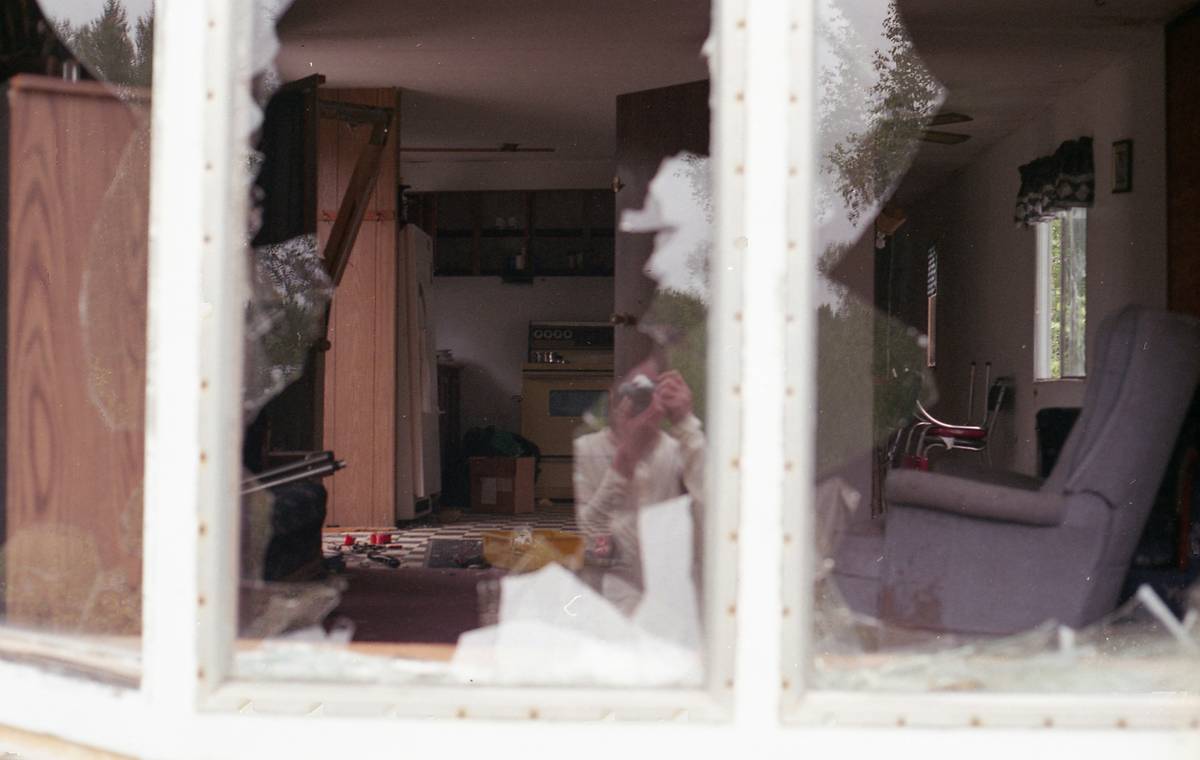
Call the police first—yes, even for small thefts. Their report is non-negotiable. Then, take timestamped photos of every entry point, scattered drawers, and missing items’ empty spaces. Don’t rearrange anything until you’ve documented it all. That includes shattered glass, forced locks, or muddy footprints.
Step 2: Compile a Dynamic Inventory
Ditch handwritten notes on napkins. Use a digital inventory app—or at minimum, a spreadsheet—that includes: item name, brand, model, purchase date, original cost, current value, and proof of ownership (receipts, warranty cards, credit card statements). For jewelry or art, include appraisal documents.
And yes—screenshots of online marketplace listings (eBay, Facebook Marketplace) showing comparable resale prices count as valid valuation support. Insurers know this; most policyholders don’t.
Step 3: Submit With Precision Timing
Filing too soon = incomplete data. Too late = suspicion of exaggeration. The sweet spot? Within 72 hours of the incident—but only after you’ve gathered core evidence. Missing this window won’t void your claim, but it invites scrutiny.
| Documentation Type | Minimum Requirement | Ideal Evidence (Speeds Up Payout) |
|---|---|---|
| Police Report | Case number & officer contact | Full PDF copy with narrative details |
| Proof of Ownership | One receipt per major item | Photo + receipt + credit card statement match |
| Damage Photos | 3–5 overall shots | Timestamped, geotagged, close-up + wide-angle |
| Inventory List | Handwritten list | Digital spreadsheet with depreciation calculations |
The Industry Secret: Claims Adjusters Prioritize “Paper Trail Coherence” Over Value
Here’s an unspoken truth from inside adjuster training manuals: they’d rather approve a $2,000 claim with flawless documentation than wrestle a $10,000 one riddled with gaps. Why? Because coherent files close faster—and faster closures mean better performance metrics for them.
So stop leading with loss amount. Lead with order. Structure your submission like a mini-audit: chronological, cross-referenced, and self-verifying. One adjuster I spoke with admitted, “If I can validate three items independently from your docs, I’ll extrapolate confidence to the rest.” That’s your leverage.
Frequently Asked Questions
What if I don’t have receipts for stolen items?
Use bank/credit card statements, product packaging, instruction manuals, or even dated photos of the items in your home. Alternative proof is acceptable—if it’s credible and consistent.
How long do I have to file a burglary insurance claim?
Most policies require notice within 60 days, but delays beyond 72 hours without justification can trigger investigations. Report immediately—even if your inventory isn’t complete.
Does my credit card offer burglary protection?
Some premium cards extend purchase protection for theft—but only for items bought with that card, and usually capped at $10,000. It’s supplemental, not a replacement for home insurance.